
How To Do A Credit Card Balance Transfer

Alright, folks, let's talk about something that's as common as your morning coffee but often shrouded in mystery - credit card balance transfers. Now, I'm not talking about some magical dance move or a secret handshake, but a financial trick that could save you a pretty penny. So, grab a cuppa, get comfy, and let's dive in!
What's the Deal with Balance Transfers?
Imagine you're at a buffet (because who doesn't love a good analogy involving food?). You've got a plate full of debt - some high-interest, some low. Now, you wouldn't keep stuffing your face with the expensive stuff when there's cheaper grub available, right? That's where balance transfers come in. It's like moving the expensive debt to a plate with a '50% off' sticker.
Why Bother?
Well, let me ask you this - would you rather pay off your debt like a snail on a salt lick, or like a cheetah on a caffeine high? Yeah, thought so. Balance transfers can give you that cheetah-like speed by slashing your interest rates. It's like going from a slow jog to a sprint, without even breaking a sweat.
But hold your horses, because there's a catch. Just like that '50% off' sticker at the buffet has a tiny 'excludes steak and lobster' print, balance transfers often come with a fee. It's usually around 3-5% of the transferred amount, so it's not chump change, but it could still be worth it if you're carrying a hefty balance.
How to Do a Balance Transfer - The Step-by-Step Guide
Step 1: Find Your Dream Card
First things first, you need to find a card that's offering a sweet intro APR (that's fancy talk for 'interest rate') on balance transfers. These offers can range from 0% to 5%, and they usually last for 12-21 months. It's like finding the perfect pair of jeans - you want something that fits your budget and makes you feel good.
But remember, just like those jeans, you might not be able to keep them forever. Once the intro period is over, the interest rate goes back up, so it's crucial to have a plan to pay off your debt before then.
Step 2: Make the Call
Alright, you've found 'the one'. Now it's time to make the call. You'll need to contact your new card issuer and ask about their balance transfer process. They'll likely give you a toll-free number to call, or you might be able to do it online. It's like ordering a pizza - easy peasy.
You'll need to provide some details about the debt you want to transfer, like the balance amount and the account number. Don't worry, it's not as scary as it sounds. It's just like giving your pizza guy your address, except you're not getting pizza in return (sorry).
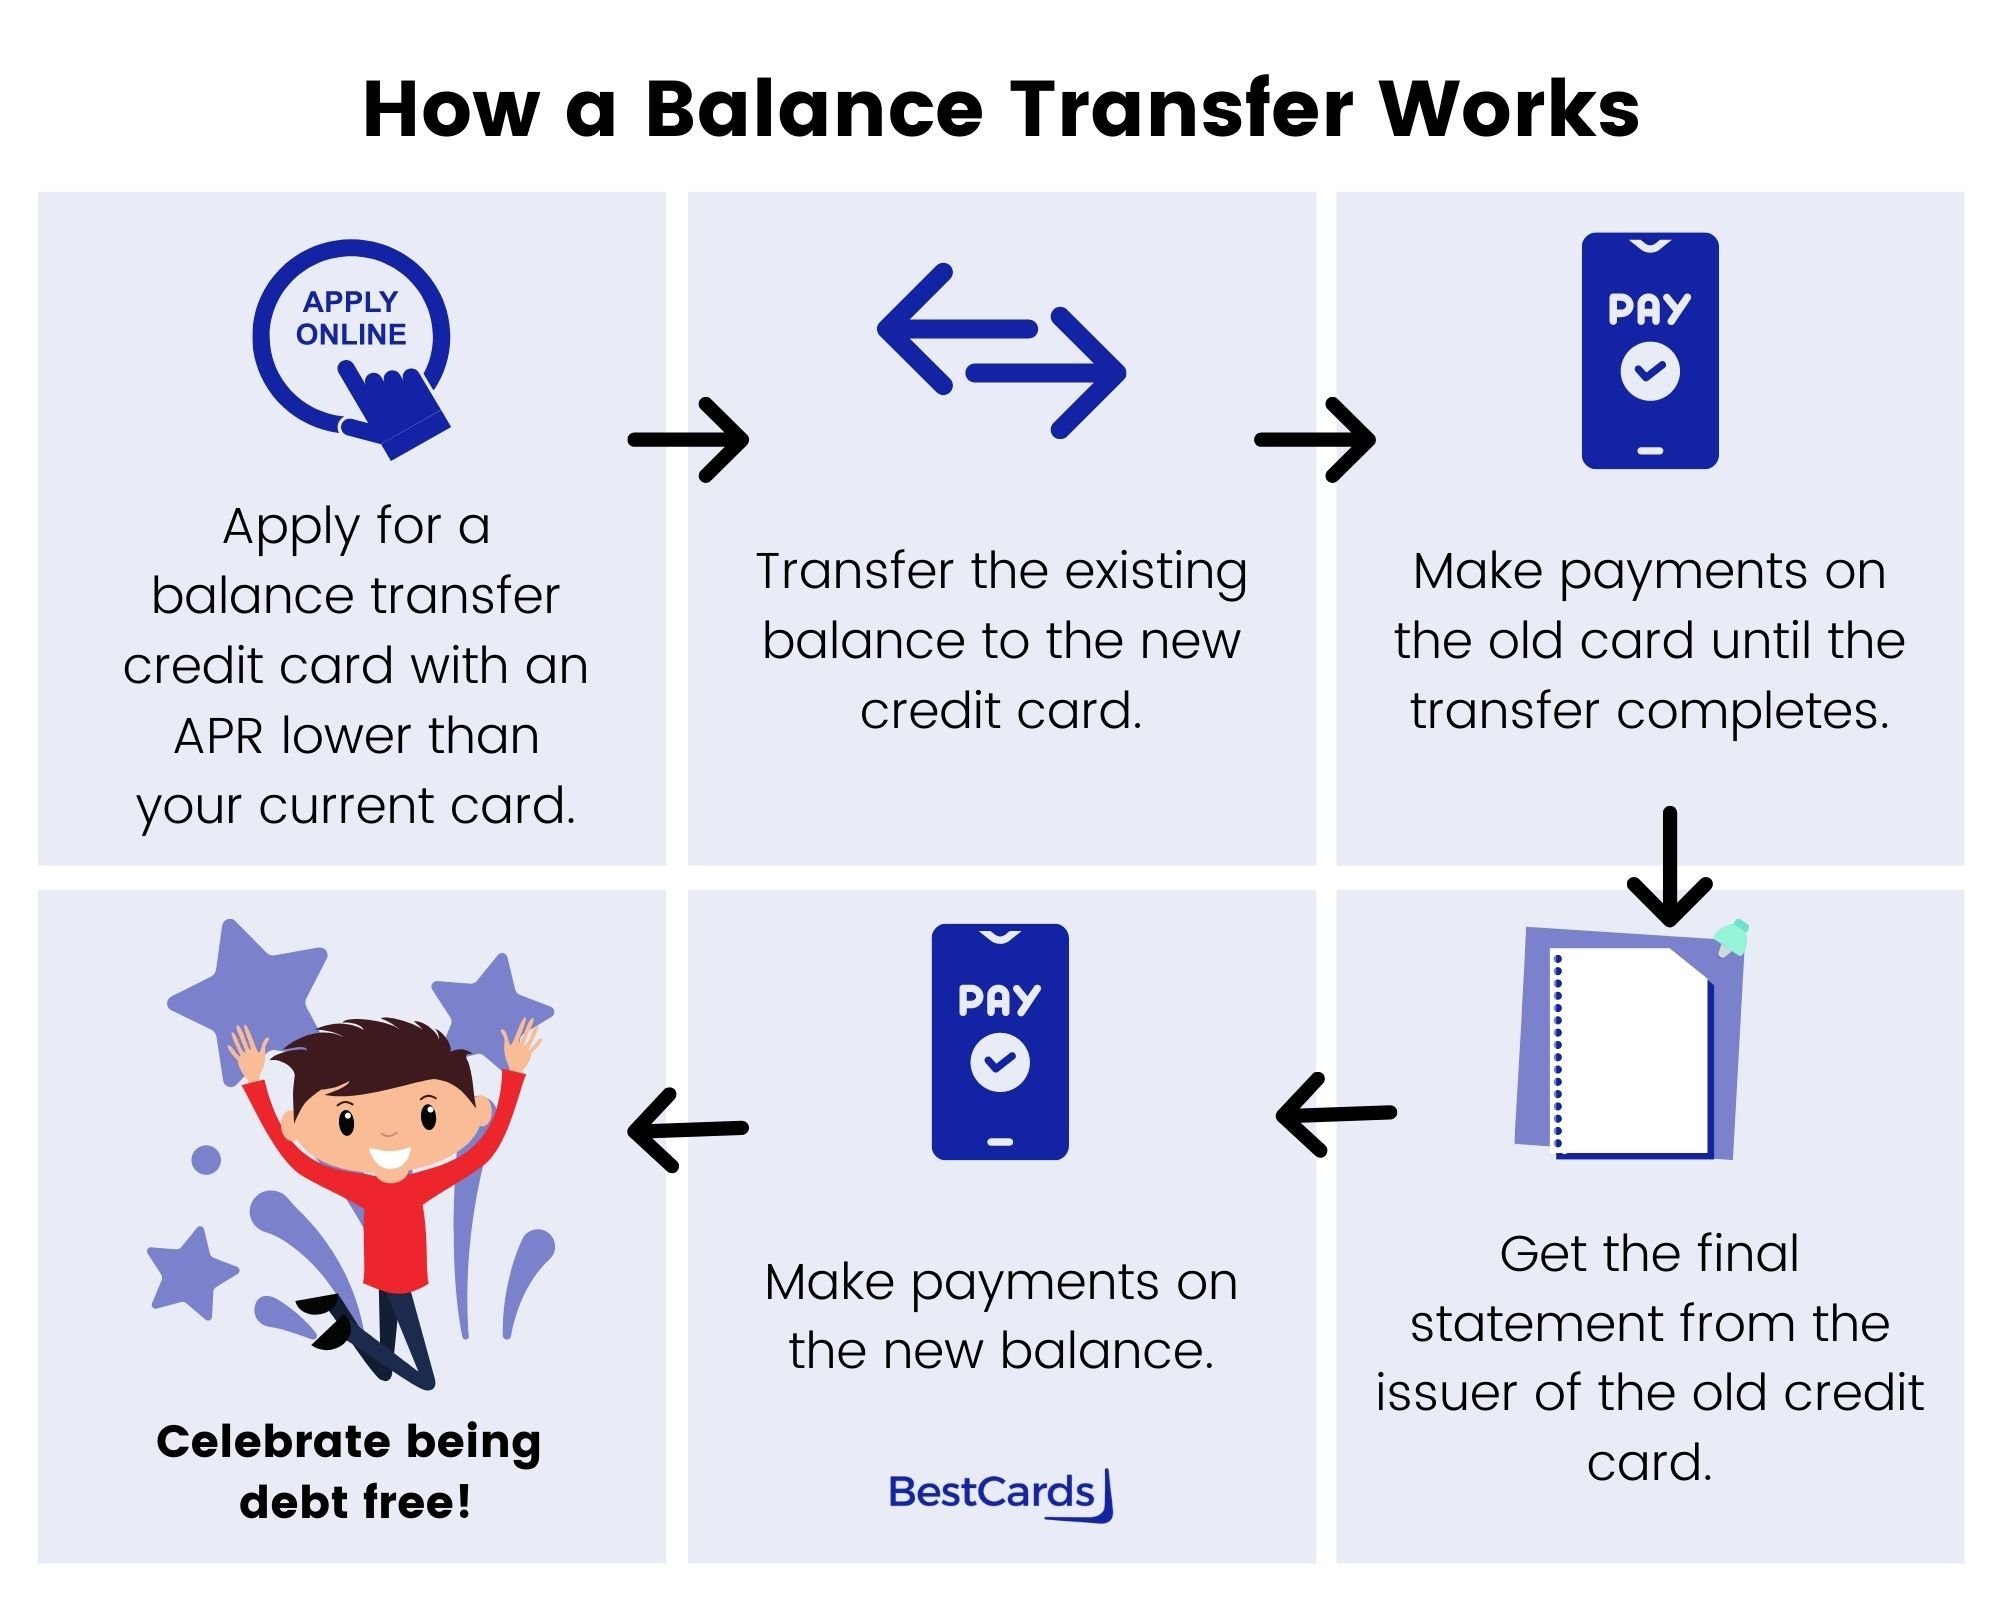
Step 3: Wait for the Magic to Happen
Once you've placed your order (I mean, initiated the transfer), it's time to sit back and wait. The process can take anywhere from a few days to a few weeks, so be patient. It's like waiting for your pizza to arrive - you know it's coming, you just don't know exactly when.
Meanwhile, keep making the minimum payments on your old card to avoid any late fees or damage to your credit score. You don't want to miss out on that cheetah-like sprint because you got a little too comfortable on your couch.
Step 4: Celebrate!
Congratulations, your balance transfer is complete! It's like finally trying on those jeans you've been eyeing, and they fit like a glove. Now it's time to celebrate by... paying off your debt. I know, I know, not the most exciting party, but think of it as a debt-free dance party in your future.
Remember to keep an eye on your statements to make sure everything transferred correctly. If something's not right, don't hesitate to give your new card issuer a call. They're there to help, and they want you to be happy with your new card (just like your pizza guy wants you to be happy with your pizza).
Some Final Tips
Before you dive headfirst into the world of balance transfers, here are a few things to keep in mind:
- Don't transfer balances just to open new lines of credit. That's like ordering a second pizza just because it's there - it might seem like a good idea at the time, but it could leave you with a stomachache (or in this case, more debt) later.
- Do make a plan to pay off your debt during the intro period. It's like setting a deadline for that diet you've been meaning to start - it's more likely to happen if you have a specific goal in mind.
- Consider using a balance transfer calculator to see if this move makes financial sense for you. It's like using a nutrition calculator to see if that second pizza will fit into your daily calorie intake. Knowledge is power, folks!
And there you have it - the not-so-mysterious world of credit card balance transfers. It's like a secret handshake that could save you a ton of money, if you know how to do it right. So go forth, find your dream card, and start your debt-free sprint!